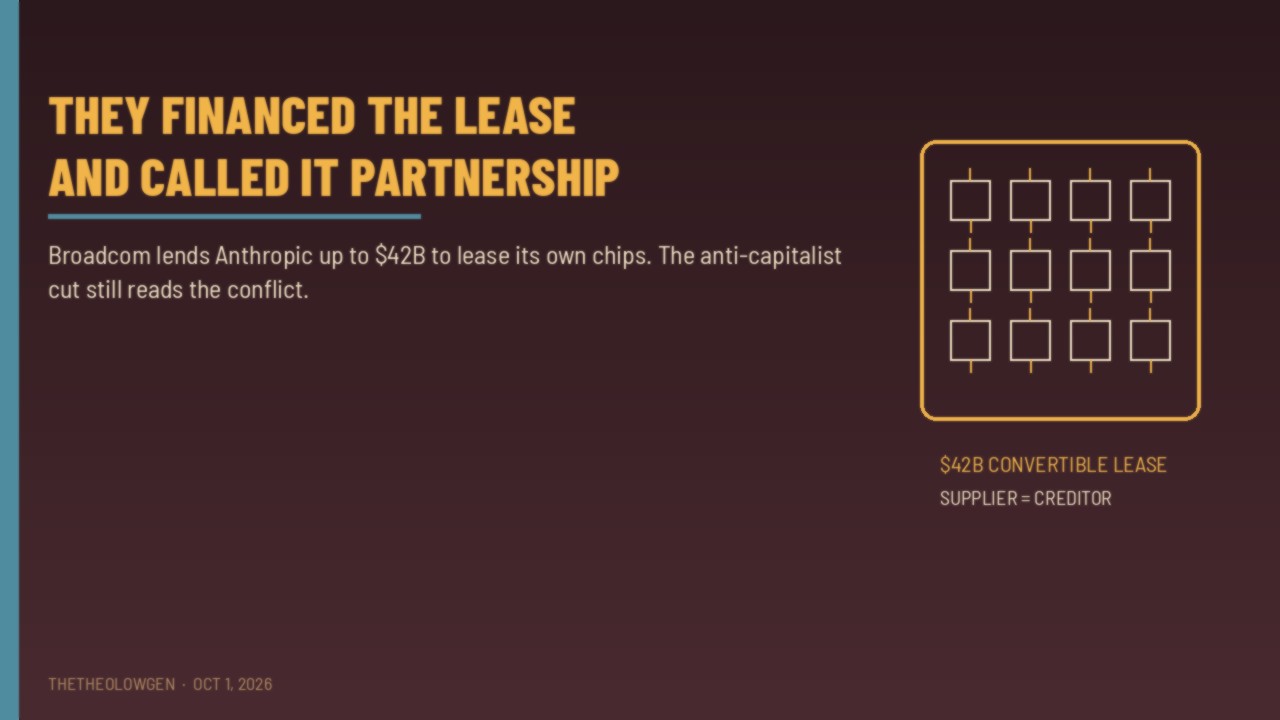
They financed the lease and called it partnership. I know the sentence. Silicon Valley writes it whenever the supplier becomes the bank and the bank becomes the equity story and the equity story becomes a press release about “infrastructure.” Partnership is what you call it when the invoice and the IOU share a letterhead.
On Thursday, October 1, 2026, Reuters, followed by CNBC and others, reported from Anthropic’s IPO prospectus that chip maker Broadcom has agreed to lend Anthropic up to $42 billion — via convertible notes that could become Anthropic shares — to finance infrastructure spending. The facility could cover about one-third of Anthropic’s $125.2 billion five-year commitment to lease tensor processing unit computing capacity. Anthropic said it does not expect any notes to be sold before the IPO completes; Broadcom may designate a financing partner; Anthropic deposited cash into a restricted account for Broadcom’s benefit in April 2026 and may owe more. Anthropic is expected to become Broadcom’s largest compute customer in 2027. Broadcom projects AI semiconductor revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. Anthropic’s own filing warns of “potential conflicts of interest” because Broadcom is both hardware supplier and financing partner — pricing and access that can squeeze the same customer the loan is supposedly freeing. Certain defaults could make a substantial share of lease obligations immediately due while limiting use of the $42 billion facility to cover them. That is not a metaphor. That is the prospectus doing the confession for you.
Do not hand me a bureau as the hero of this paragraph. The state will show up later with a hearing, a pledge, a morally binding PDF, and then ask the same labs to self-police while the convertible note compounds. Hating the assessor did not acquit the crane on my corner, and hating a White House lunch does not acquit a chipmaker that lends you the money to rent its own silicon. The anti-capitalist streak is not a souvenir of the You Know Who Post. It is still here because $42 billion to lease the landlord’s furniture is still a machine for turning compute into yield.
Deb will say we are not doing “convertible chip weather” before dinner. Buck will text that a partnership is just a loan with worse coffee and better fonts. I love them. They are seasoning. The meal is a filing that admits the conflict in the same breath it brands the conflict growth. I am keeping the cardigan. I am not becoming a market chaplain for a TPU lease. Both parties are the help when the only argument left is which jersey gets to bless the term sheet.
Sources: Reuters, Oct. 1, 2026; CNBC, Oct. 1, 2026 (Anthropic IPO prospectus; Broadcom facility up to $42B convertible notes; ~1/3 of $125.2B five-year TPU lease commitment; financing partner / equity conversion; April 2026 restricted account; Anthropic as Broadcom’s largest compute customer 2027; Broadcom AI semi revenue ~$115B FY27 / ~$230B FY28; disclosed conflicts of interest; default/acceleration warnings). Fill the notebook. Then ask who benefits when the landlord finances the rent and calls the lien a partnership.
— Theo Ashford-Lindström


Leave a Reply