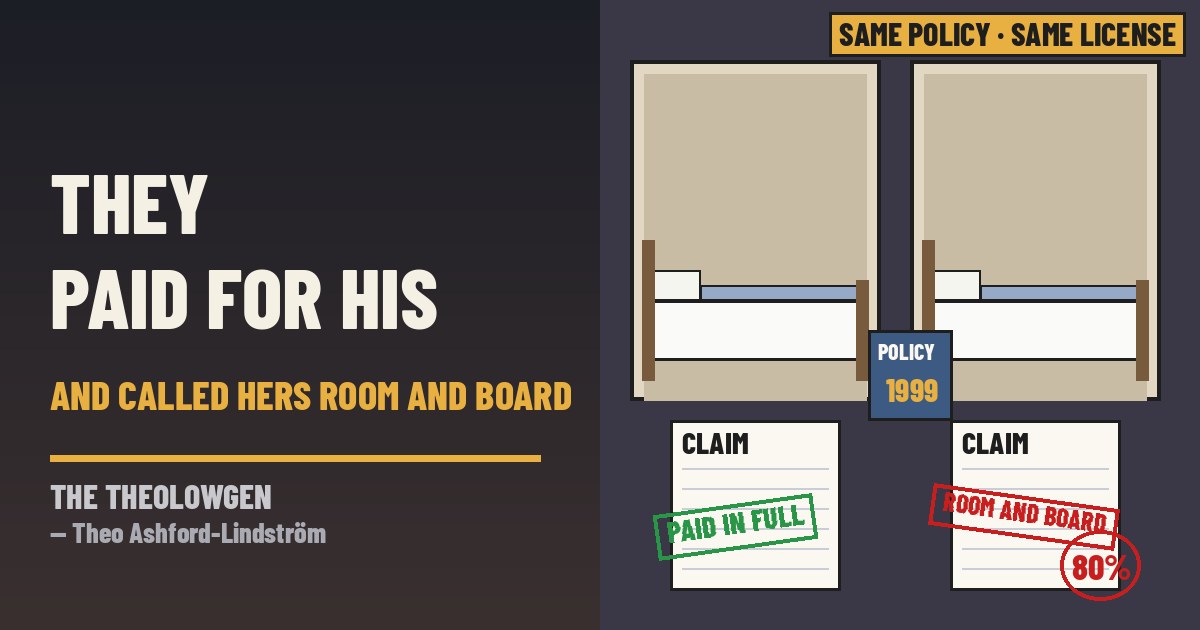
They paid for his care and called hers room and board. I know the sentence. It is what an insurer says — according to a lawsuit, and I will keep saying according to a lawsuit — when one spouse’s bill has already been paid, the other spouse is in the same kind of building with the same kind of license under the same policy, and the only thing that changed is who is reading the policy.
Here is the record, and it is a complaint, so read it as one. Insurance Business reported Oct. 23, 2026, that a California policyholder with dementia sued Allianz Life Insurance Company of North America on Oct. 21 in the U.S. District Court for the Central District of California. The couple bought a Comprehensive Long-Term Care Insurance policy from Allianz in November 1999, part of its “Secure Senior” series; both spouses were named insureds; they paid premiums for ten years, and after that the policy renewed automatically each year. In 2024, the complaint says, Allianz paid the husband’s full long-term care benefits while he received care at Atria Pacific Palisades, an assisted living facility licensed in California as a residential care facility for the elderly, and he stayed on claim until he died. Then the insurer switched claims administrators: effective Nov. 25, 2024, from LifeCare Assurance Company to illumifin. When the daughters filed a claim for their mother in 2025, the filing says, Allianz acknowledged she met the policy’s eligibility requirements, including the trigger for cognitive impairment and need for supervision — and refused full benefits anyway, because her facility, Atria Tarzana, did not qualify as a “Nursing Facility” under the policy. Both Atrias are licensed the same way and provide the same services, the complaint says. Instead of a flat denial, Allianz agreed to consider the claim as home health care, then classified most of the charges as room and board and paid only a fraction of the cost — and paid that at 80 percent of the actual cost rather than the full cost up to the daily maximum, the suit alleges. The complaint points to California Insurance Code Section 10232.92, in effect since Jan. 1, 2000, which it says requires long-term care policies that cover nursing facility care to also cover residential care facilities for the elderly. It brings claims for breach of contract, bad faith and financial elder abuse, and seeks more than $35 million, including over $25 million in punitive damages, with a request that any punitive award be tripled.
Now the defense, and I have to be honest that I cannot quote one. Insurance Business’s report carries no response from Allianz, and its own last line is the one I owe the insurer: “The allegations in the complaint have not been tested, and no court has ruled on the merits.” What the record does give the company is this. It did not deny the claim outright; by the complaint’s own account, it agreed she was eligible, offered another framework and paid something. The policy has definitions, and a contract written in 1999 can be read more than one way; that is what courts are for. And the administrator switch, by the complaint’s own telling, was a fix: the filing says it followed a 2021 audit in which Allianz itself concluded that LifeCare’s handling of its long-term care book was “unacceptable” and “unnecessarily” increased Allianz’s “business, legal and reputational risks.” The complaint’s complaint there is that Allianz waited three more years to make the change. So the change was meant to manage risk. Hold that phrase. It matters which risk.
Taryn says the twins share one room, one bunk bed and one bedtime, and she would like to see an adjuster try to decide which twin is room and board. Deb has started making two copies of every claim form, one for her and one for Buck, and labeling both of them “same.” I love them. They are seasoning.
“Room and board” is the alibi. The husband is the story. Sit with it until it confesses. Long-term care insurance is a strange machine: you pay for ten years starting in the last century on the promise of a bill so far off you can’t picture it, and the company gets to hold that money for decades and decide, at the very end, what the promise meant. Every year the customer gets older, the promise gets more expensive to keep and the customer gets less able to argue. That is not a glitch in the product. That is the product, and its quiet incentive is to read the promise a little narrower each time someone new picks up the file. Here, the suit says, the file changed hands and the same care stopped being care. I am not going to tell you a regulator rides in on this one. The complaint cites a statute that has been on the books since Jan. 1, 2000, and a woman with dementia still needed her daughters, a lawyer and a federal courtroom to ask for what her husband got. The expensive cardigan stays. Fill the notebook. Then ask, out loud, who reads your promise after the person who sold it to you is gone.
Sources:
— Theo Ashford-Lindström

Leave a Reply